Does Insurance Cover Windshield Replacement in Tennessee?
Yes, if you carry comprehensive coverage. But Tennessee has no law waiving your glass deductible, so whether you pay $0 comes down to your policy. Here's how to tell before you file.
Comprehensive coverage pays for windshield replacement in Tennessee, but your comprehensive deductible applies. Tennessee has no zero-deductible glass statute. The only reliable route to $0 is an optional full glass endorsement on your policy, which typically runs $30 to $60 a year. Chip repair is the exception: most carriers waive the deductible on a repair as a business decision, because a $100 repair is cheaper for them than a $400 replacement later.
What Coverage Type Covers Windshields?
Windshield damage is an other-than-collision loss, meaning it's covered under comprehensive coverage, not collision. Comprehensive covers:
- Rock chips and cracks from road debris
- Hail damage
- Vandalism (e.g., someone breaking your window)
- Weather events (falling branches, storms)
- Theft-related glass damage
If your windshield was damaged by a collision with another vehicle or a stationary object (a pole, a wall), that's a collision claim, handled differently and your standard deductible applies.
What Tennessee Law Actually Says About Glass Deductibles
Tennessee does not have a zero-deductible glass law. Three states do mandate full glass coverage or a deductible waiver on comprehensive glass claims: Florida, Kentucky and South Carolina. Tennessee is not one of them. If a shop tells you “state law makes it free,” they are either confusing Tennessee with Florida or they are selling you something.
Your comprehensive deductible does apply to a glass claim in Tennessee. If your comp deductible is $500 and the replacement is $420, insurance pays nothing and the claim is pointless. If the deductible is $100 and the job is $620, you pay $100.
What Tennessee law does regulate is how glass shops behave. Under Tenn. Code Ann. § 56-7-1114, it is an unfair and deceptive act for a glass shop to offer you a credit, gift, rebate, or financing toward your deductible, or to advertise glass work as free when an insurer is footing the bill. Section 56-7-1115lets your insurer demand verified proof that you actually paid the deductible before they settle. So a shop “eating your deductible” is not a favour, it is a violation that can get your claim denied.
The practical takeaway: in Tennessee, a broken windshield is not automatically free. Knowing your deductible number before you file is what decides whether a claim is worth opening at all.
How to Check Whether Your Policy Gets You to $0
Pull up your declarations page and look for three things. It takes about two minutes and tells you exactly what a claim will cost you.
Is comprehensive listed at all?
Liability-only policies, which are common on older paid-off vehicles, cover nothing for your own glass. If there is no comprehensive line, the replacement is out of pocket.
What is the comprehensive deductible?
It is printed next to the comprehensive line, usually $100, $250, $500, or $1,000. Compare it to the quoted replacement price. If the deductible is higher, do not file.
Is there a glass or safety glass endorsement?
Look for a line reading full glass, glass coverage, or safety glass buyback. That is the optional add-on that drops the glass deductible to $0. It costs roughly $30 to $60 a year and it is the only dependable way a Tennessee driver pays nothing.
If you cannot find your declarations page, your carrier's app or a two-minute call to your agent will answer all three. Ask the question this way: “What is my comprehensive deductible, and do I have a glass endorsement?” Compare that answer with a cash quote before you book anything.
Why Repair Is Usually the $0 Option, Not Replacement
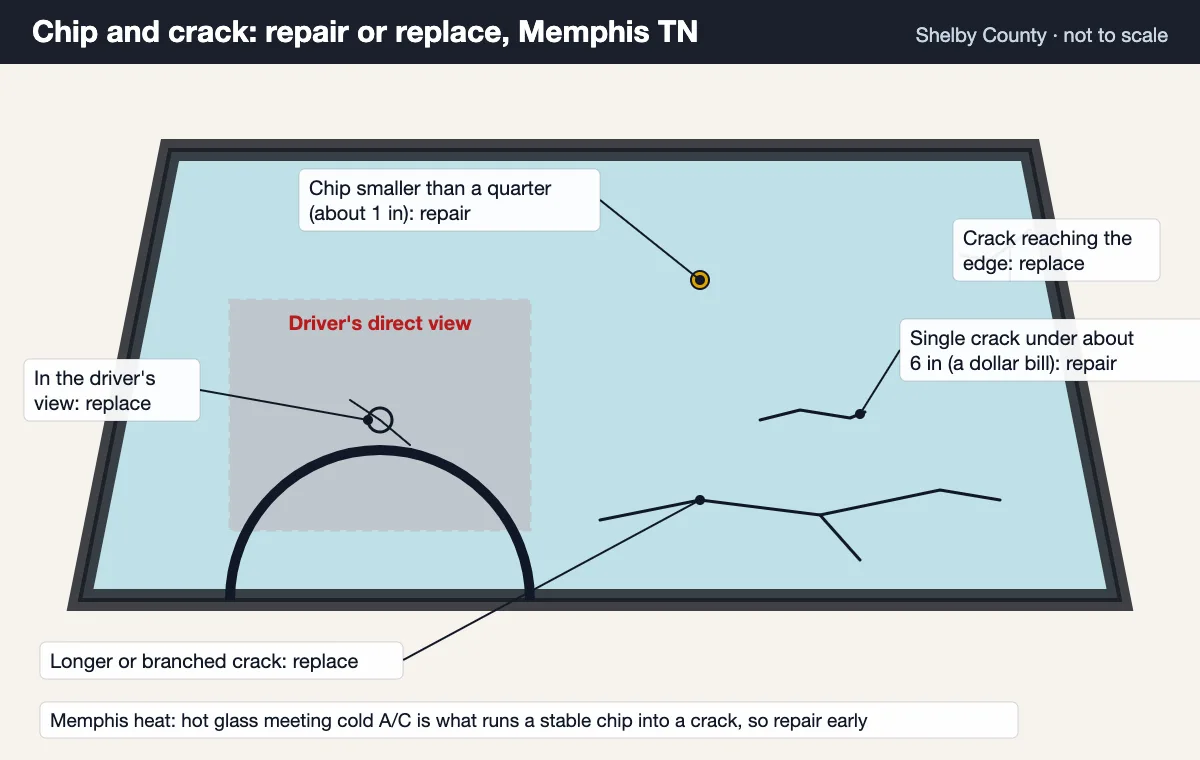
Most major carriers waive the deductible on a chip or short-crack repair even though no law requires it. A resin repair costs them $85 to $160. A replacement runs $176 to $767 in Memphis, plus $100 to $300 when a windshield camera needs recalibration. Waiving the cost of a repair to avoid paying for a replacement is straightforward math for an adjuster.
That waiver almost never extends to replacement. So if your damage is still small enough to repair, filing immediately is usually free and it protects the glass you already have. Our repair vs. replace guide covers the size and location rules that decide which one you are looking at.
Will Filing a Glass Claim Raise My Rates?
Usually not. A glass claim is a comprehensive, not-at-fault loss, and most carriers do not surcharge a single comprehensive claim the way they surcharge an at-fault collision.
The honest caveat: no state law stops a Tennessee insurer from considering comprehensive claim frequency at renewal. Repeated glass claims in a short window can move you to a less favourable tier with some carriers. One chip repair is a non-event. Three replacements in two years is worth a conversation with your agent first. If you are unsure, ask your agent the direct question before a claim is filed, and hold off on booking until you have the answer.
Your Right to Choose Your Shop
You pick the shop, not your insurer. When you call a claim in, the carrier routes you through a third-party glass administrator that will offer you a network shop first. That is a recommendation, not a requirement. Tell them the shop you want and they will process the claim there.
If a representative implies a non-network shop won't be covered, ask them to confirm that in writing. In practice they will not, because steering you away from your chosen shop is not something carriers want on record. One caveat worth knowing: a network shop has a pre-agreed price with the insurer, so an out-of-network shop occasionally leaves a small balance if its price is above the carrier's schedule. Ask any shop whether they bill the insurer directly and whether you will owe a difference, and get that number before you book.
How a Glass Claim Usually Runs
When you use insurance for a windshield replacement, here's what the process typically looks like:
You share your carrier and policy number
That is usually enough for a glass shop to get started.
Coverage is verified
Someone, you or the shop, confirms with your insurer that comprehensive is active, what your glass deductible actually is, and whether a glass endorsement drops it to $0. You should hear the real number before anything is scheduled, including the cases where filing isn't worth it.
The claim is opened
The glass claim is opened with your insurer or its glass administrator, and the required documentation is submitted.
The work is done
Once the claim is approved, the appointment is scheduled, in a shop or mobile.
Insurer pays the shop directly
With direct billing, the shop bills the insurer for the covered portion. You pay your deductible, or nothing at all if you carry a glass endorsement.
Major Carriers in Memphis
Frequently Asked Questions
Does insurance cover windshield replacement in Tennessee?
Yes, if you carry comprehensive coverage. Windshield damage from road debris, hail, vandalism or storms is an other-than-collision loss, so it goes through comprehensive, and your comprehensive deductible applies.
Is there a zero-deductible glass law in Tennessee?
No. Florida, Kentucky and South Carolina mandate full glass coverage or a deductible waiver; Tennessee does not. The reliable route to $0 is an optional full glass endorsement, which typically runs $30 to $60 a year.
Is chip repair free with insurance?
Often. Most carriers waive the deductible on a chip repair as a business decision, because a $100 repair costs them less than a $400 replacement later.
Can a glass shop pay my deductible for me?
No. Under Tenn. Code Ann. 56-7-1114 it is an unfair and deceptive act for a glass shop to offer a credit, gift, rebate or financing toward your deductible, and section 56-7-1115 lets your insurer ask for proof you paid it.
Submit a free quote request, and check your deductible and endorsement before anything gets scheduled, so you know exactly what you owe first.
Insurance Claims Page →